The importance of customer data integration into making smarter, more appealing offers to bank customers has never been more important. Financial institutions and technology partners are working to combine behavioural cues, attribute preferences, and transactional metrics to optimise the customer experience and create long-term lifetime value.
The importance of customer experience in building banking relationship loyalty
I recently attended the FinovateFall 2026 conference held in New York in September. One of the three core topics of attention at the event focused on customer experience optimisation for bank customers. According to Euromonitor's Voice of the Consumer: Loyalty Survey, fielded January to March 2026, 27% of consumers globally agree loyalty programmes should be more personalised, reflecting a broader expectation that financial institutions must compete on experience quality, not product availability alone. With this top of mind among attendees and panel speakers, there has been a shift in mindset on how financial institutions need to view and prioritise customer experience.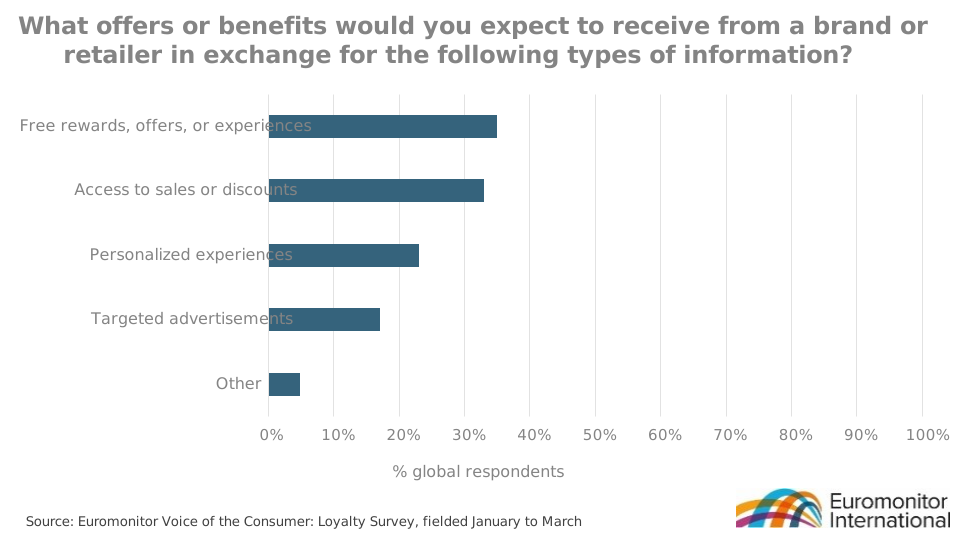
Technology is now being deployed to harness the power of customer data to tailor experiences with the intention to create stickiness and loyalty. Loyalty engines and customer data platforms deliver real-time insights that can be shared across functions within banks to deliver contextual, non-intrusive offers at the point of need.
Bank loyalty programmes rebuilt around primacy and cross-product relationships
Bank loyalty programmes are being rebuilt around primacy and cross-product relationships, not card spend alone. Ally Financial just announced its Loyally loyalty programme launch after piloting it earlier this year and rolling it out to all customers in May 2026, with the programme living solely on the bank’s mobile apps, focused on experiential benefits through the VIP Experiences perk. Rewards are available regardless of account balance, the programme carries no fees, and some perks are personalised, such as a bonus offer to open an Ally investing account. Bank of America replaced its Preferred Rewards programme with BofA Rewards, also in May 2026, now offering free identity and fraud monitoring, discounts on insurance and investment products, and cashback deals at more than 15,000 merchants. PNC has taken a slightly different approach – PNC TotalRewards is a tier-based loyalty programme based on deposit and investment balances, with 5-35% in bonus points or cashback rewards tied to credit card spending depending on tier status.
Personalisation is moving from static segments to the “segment of one”
Personalisation is moving from static segments to a “segment of one”, triggered in real time. There were multiple AI-based platforms at FinovateFall 2026 showcasing how bank customer data can be better leveraged. For example, Ventus AI combines proprietary transaction enrichment with external intelligence to identify behavioural, life-event, demographic, financial, and risk signals per customer. Vertice's CORE and ACQUIRE modules score customer engagement, predict next products, and identify high-potential prospects using enriched Experian data, without needing to hire data scientists. OptimaFI benchmarks institutional data against more than 14 billion private peer data points and provides segment-level recommendations related to growth and risk, and because it does not require a core integration, financial institutions can begin using the platform in a matter of days. Rewards are being tied to good financial behaviour such as saving, paying down debt, and repaying on time. Debbie's Rewards 2.0 pays one point per dollar that is deposited into savings or applied towards credit card balances, and 1.5-2 points on eligible partner bank or credit union savings accounts. Among the banks that spoke at the event, Truist says clients have received more than two billion proactive financial insights and advice through Truist Insights since 2023.
Banks and financial institutions will need to adopt the loyalty supply chain ecosystem data tools that leaders in travel, retail and foodservice have been leveraging for years, or risk being left behind and suffer customer attrition.
Discover the latest loyalty insights and perspectives, here.