The pressure on household budgets is not easing in 2026. Inflation is set to climb to 4.9%, real income per capita growth is expected to ease to 1.3%, spending growth to 1.1%, and confidence remains fragile across much of the world. Consumers are not spending less so much as spending differently, reallocating with intent and resetting category hierarchies as they go. Three major shifts will define where the money moves this year: macro shocks, that now hit wallets in days; the consumer pool, which is splitting in two; and time becoming the currency brands compete for.
Macro shocks hit wallets instantly
Geopolitical shocks now change consumer behaviour before they reach the shelf. During the last major tariff wave, inflation expectations surged and sentiment fell towards record lows well before prices moved. That transmission is accelerating in 2026. The US/Israel-Iran war has weakened confidence and trust, while disruption in the Strait of Hormuz has renewed pressure on input costs. In a digitally connected, news-saturated market, consumers can shift spending intentions within days of a headline, leaving brands almost no time to respond. Stability is therefore becoming a competitive advantage.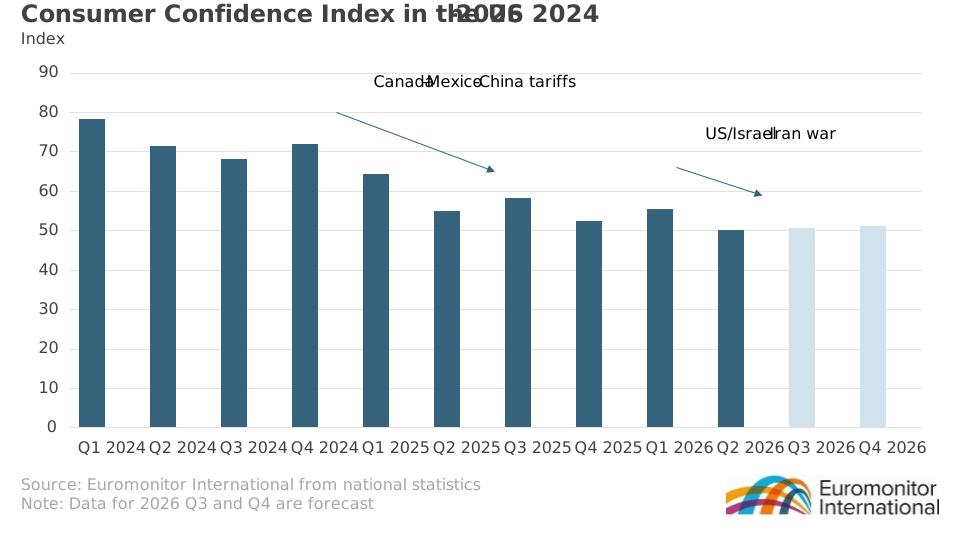
In 2025, Home Depot publicly committed to holding prices across much of its range while competitors warned of increases. Its long-standing supply-chain diversification made the pledge credible, but communication was equally important: by signalling stability as consumers reassessed their spending, it turned uncertainty into trust. The lesson is clear: brands cannot control geopolitical shocks, but they can control how those shocks reach consumers.
Two consumers, one market
The consumer market is polarising at both ends simultaneously – and the middle is bearing the cost. Social classes A and E were the two fastest-growing income groups globally in 2025, each projected to expand by 14-15% by 2040, while the middle-income segment contracts. This is structural, not cyclical. Crucially, the shift is not only income-driven – behavioural contrasts are intensifying alongside income divides, as consumers at both ends develop different values, digital preferences and identity motivations.
Importantly, high-income earners do not shy away from lower-cost options, such as private label, while low-income consumers have not abandoned brands.
43% of the respondents earning less than USD20,000 annually (lowest income segment) say they prefer branded goods to non-branded ones, while 26% regularly seek strong or well-known brands.
Source: Euromonitor's Voice of the Consumer: Lifestyles Survey, fielded January to February 2026
Retailers are already building for the split. Kroger, for example, runs a 4-tier own brand from opening-price to premium – around USD30 billion in value – competing across the entire income spectrum at once.
Time is the new wallet
Money increasingly follows time too. In 2026, 68.5% of consumers are actively trying to simplify their lives and free up hours. Yet they are spending more on experiences – travel, dining, leisure. Where they choose to spend those hours now determines where they spend their money. So, brands are no longer competing only for wallet share; they are competing for a place in leisure, community and social ritual. 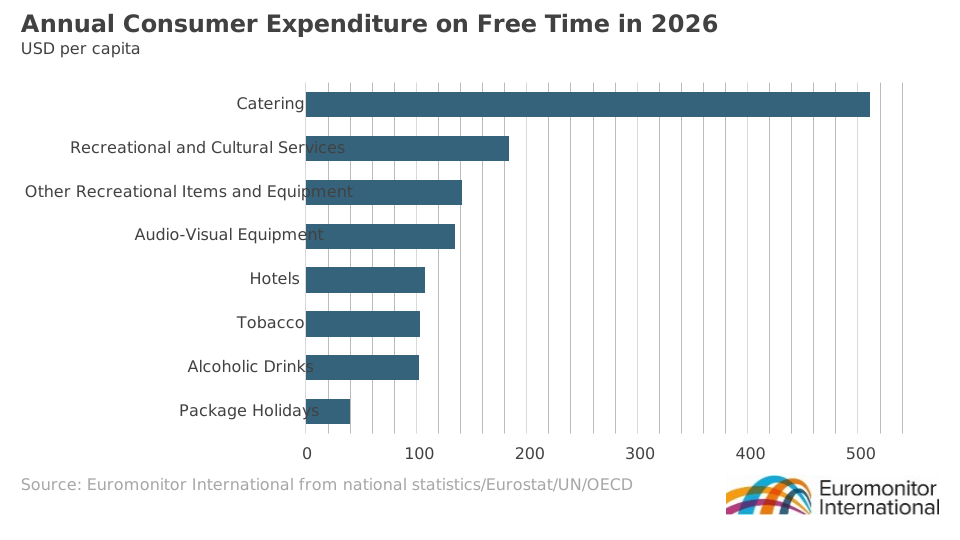
The strongest brands are not interrupting leisure – they are becoming it. Heineken’s Social Off Socials created phone-free gatherings, positioning the brand as a host of real connection rather than another bid for screen time.
The thread through all three shifts is the same. Consumers are reallocating with intent, and the brands that grow in 2026 and onwards are those that answer the new questions first – before the shock, before the split, before the moment closes.
Download our full briefing, Top Five Trends in Income and Expenditure, for the two further shifts – a permanent reset of the household basket and health as the lens over every category – with more case studies and strategic recommendations.